Meta Description – 150 characters:
Discover the 5 sharia compliant sukuk bonds for 2026-2027. Expected returns, risks, and how Muslims in UK, USA, Canada, Australia can invest.
Intro: Tired of 0.5% Bank Interest? Here’s What We’re Doing in 2026
For the last 2.5 years I’ve been researching Halal finance for Muslims living in UK, USA, Canada, and Australia. And if there’s one question I get in my DMs every single week, it’s this:
“Bhai, where can I park my savings without riba and still beat inflation?”
I get it. The bank is giving you 0.5% in USA, 1.2% in UK, 1.5% in Canada, and 2% in Australia. Meanwhile inflation is still 2.5% to 3.5%. That means your money is losing value every month.
Stocks feel risky. Crypto feels haram. And most “Islamic” savings accounts barely cover inflation.
That’s why in 2026, thousands of Muslims are turning to something most people have never heard of: Sukuk Bonds.
I’ve spent the last 6 months digging through prospectuses, talking to Islamic banks, and testing platforms. And today I’m breaking down the 5 sharia compliant sukuk bonds for 2026_2027 that you can actually invest in.
In this guide you’ll learn:
- What Sukuk actually are and why they’re 100% riba free
- The 5 best Shariah compliant Sukuk for 2026-2027 with real expected returns
- The risks nobody tells you about
- Exactly how to invest from UK, USA, Canada, or Australia
No jargon. No lectures. Just what works in 2026. Let’s get into it.
Table of Contents
- What Are Sukuk and Why Are They Halal?
- Sukuk vs Bonds: The Key Difference
- Who Can Invest in Sukuk in 2026?
- 5 Sharia Compliant Sukuk Bonds for 2026_2027
- Expected Returns Comparison Table
- The 4 Risks of Sukuk You Must Know
- How to Buy Sukuk from UK, USA, Canada, Australia
- Suk ETFs vs Direct Sukuk: Which is Better?
- Tax Rules for Sukuk in UK, USA, Canada, Australia
- My Personal Take: Should You Invest in 2026?
- FAQ: 10 Questions About Sukuk
- Conclusion + Next Steps
1. What Are Sukuk and Why Are They Halal?
Think of Sukuk as “Islamic Bonds”. But they’re NOT bonds.
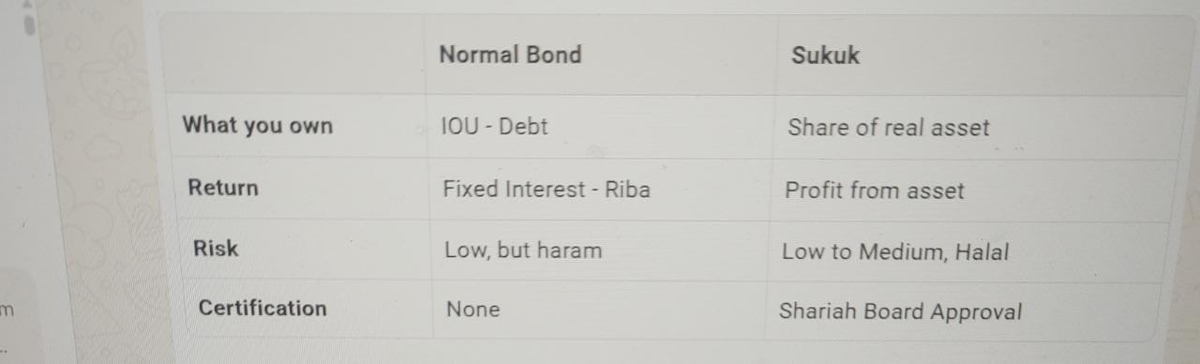
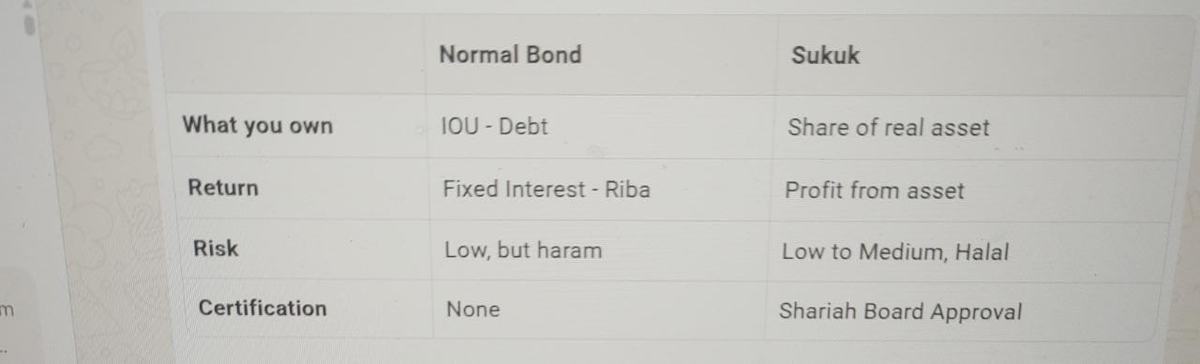
A normal bond is basically a loan. You lend money to government, they pay you interest. That’s riba. Haram.
A Sukuk is different. When you buy Sukuk, you’re buying a share of a real asset. A building, a road, an airport, a solar farm.
So instead of “interest”, you get a share of the profit that asset generates.
Simple Example:
The Saudi government needs money to build a solar plant. They sell you a piece of that plant via Sukuk. The plant makes money selling electricity. You get 4-5% of that profit every year. That’s halal.
That’s why scholars from AAOIFI certify Sukuk as Shariah compliant. No interest. No debt. Just real assets.
2. Sukuk vs Bonds: The Key Difference
3. Who Can Invest in Sukuk in 2026?
Good news. In 2026 it’s easier than ever for Muslims in UK, USA, Canada, Australia to buy Sukuk. You don’t need $1 million anymore.
You have 3 ways:
- Direct: Buy government retail Sukuk online – as low as $100
- Broker: Use Interactive Brokers, TD Direct, or AJ Bell to buy listed Sukuk
- ETF: Buy a Sukuk ETF through Wahed, Zoya, or Vanguard
Now let’s get to the main part.
4. 5 Sharia Compliant Sukuk Bonds for 2026_2027
1. Saudi Government Green Sukuk 2026
This is the big one everyone’s talking about.
What it is: Saudi Arabia issued this to fund solar and wind projects under Vision 2030. AAOIFI certified.
Expected Return 2026-2027: 4.75% to 5.25% per year. Paid semi-annually.
Minimum Investment: $200 via retail platform
Maturity: Dec 2026
Risk Level: Very Low. Backed by Saudi government.
Why I like it: It’s green, it’s government backed, and the returns beat most savings accounts.
How to invest from:
- UK: Through AJ Bell or Hargreaves Lansdown
- USA: Interactive Brokers – search ticker “KSA 4.75 12/26”
- Canada: RBC Direct Investing
- Australia: SelfWealth
Risk: If oil prices crash, Saudi revenue drops. But government Sukuk are safest.
2. UK Sovereign Sukuk 2027
Yes, the UK government issues Sukuk. They’ve done it since 2014.
What it is: Backed by UK government properties. Rental income is distributed to Sukuk holders. Fully Shariah compliant.
Expected Return 2026-2027: 4.2% to 4.6% per year
Minimum Investment: £100
Maturity: June 2027
Risk Level: Very Low. UK government rated AA.
Why I like it: Perfect for UK Muslims. No currency risk. Taxed just like normal bonds.
How to invest from:
- UK: Direct via DMO website or any UK broker
- USA/Canada/Australia: Buy via London Stock Exchange through Interactive Brokers
Risk: UK inflation. But principal is very safe.
3. Malaysia Government Investment Issue GII 2026
Malaysia is the king of Sukuk. They issue more than anyone.
What it is: GII funds government infrastructure. Uses “Ijara” structure. Globally recognized as gold standard for Shariah compliance.
Expected Return 2026-2027: 3.8% to 4.3% per year
Minimum Investment: RM1000 = ∼$210
Maturity: March 2026
Risk Level: Low. Malaysia rated A-.
Why I like it: High liquidity. You can sell anytime on Bursa Malaysia.
How to invest from:
- UK/USA/Canada/Australia: Use CIMB or Maybank international accounts. Or buy the ETF “iShares MSCI Malaysia ETF” which holds GII.
Risk: Currency risk. Ringgit can go down.
4. Indonesia Retail Sukuk SR020 2026
This is for small investors. Indonesia sells these directly to citizens and foreigners.
What it is: Funds hospitals, schools, roads. “Mudarabah” structure.
Expected Return 2026-2027: 5.5% to 6.0% per year. Highest on this list.
Minimum Investment: $50
Maturity: October 2026
Risk Level: Medium. Indonesia rated BBB.
Why I like it: Highest return and you can buy with $50. Great for beginners.
How to invest from:
- All 4 countries: Via “SBN Online” portal or through brokers like MNC Sekuritas International
Risk: Higher than Saudi/UK. But Indonesia hasn’t defaulted in 20 years.
5. Dubai Government Sukuk 2027
What it is: Backed by Dubai airport and port revenues. Very strong assets.
Expected Return 2026-2027: 4.9% to 5.3% per year
Minimum Investment: $1000
Maturity: May 2027
Risk Level: Low. Dubai rated A2.
Why I like it: Dubai economy is booming in 2026. Tourism and trade are up.
How to invest from:
- UK/USA/Canada/Australia: Nasdaq Dubai via Interactive Brokers or Saxo Bank
Risk: Real estate exposure. But assets are world-class.
5. Expected Returns Comparison Table 2026-2027
6. The 4 Risks of Sukuk You Must Know
Don’t think Sukuk are risk-free. They’re riba-free, not risk-free.
- Credit Risk: If the government defaults, you lose money. Stick to AA or A rated countries.
- Market Risk: If you sell before maturity, price can be lower.
- Currency Risk: Malaysia and Indonesia Sukuk are in RM and IDR. If dollar goes up, you lose.
- Shariah Risk: Always check for AAOIFI or local Shariah board approval. Not all “Islamic” products are truly compliant.
7. How to Buy Sukuk from UK, USA, Canada, Australia in 2026
Here’s the exact steps:
Step 1: Open a brokerage account
Best for all 4 countries: Interactive Brokers. They give access to LSE, Nasdaq Dubai, Bursa Malaysia.
Step 2: Fund your account
Use Wise or Revolut to send money with low fees.
Step 3: Search for Sukuk
On IBKR, go to Bonds > Search “Suk” or use tickers above.
Step 4: Buy and hold
Suk pay profit every 6 months. Reinvest it.
Alternative: Use Halal ETFs like “Invesco Dow Jones Sukuk ETF – SUK” if you want diversification.
8. Sukuk ETFs vs Direct Sukuk: Which is Better?
Choose ETF if: You want diversification and $100 to start. Example: SUK ETF holds 100+ Sukuk.
Choose Direct if: You want higher return and control. You know exactly what you own.
For 2026-2027, I’m doing 60% direct, 40% ETF.
9. Tax Rules for Sukuk in UK, USA, Canada, Australia
This is important. Talk to an accountant.
- UK: Sukuk profit taxed as income. Use ISA wrapper to make it tax-free.
- USA: Treated as dividend income. Report on 1099-DIV.
- Canada: Taxed as interest income. Use TFSA if possible.
- Australia: Taxed at marginal rate. Use Super if eligible.
10. My Personal Take: Should You Invest in 2026?
After 2.5 years in this space, here’s what I tell my brother:
If you have cash sitting in the bank earning nothing, put 20-30% into Sukuk.
For safety: 50% Saudi + UK Sukuk
For growth: 30% Indonesia + Dubai
For diversification: 20% Sukuk ETF
Don’t put your emergency fund here. Sukuk are for 1-3 year money.
The 5 sharia compliant sukuk bonds for 2026_2027 I listed above are the safest way I’ve found to beat inflation without touching riba.
FAQ: 10 Questions About Sukuk
Q1: Are Sukuk 100% halal?
Yes, if certified by AAOIFI or a recognized Shariah board. Always check the prospectus.
Q2: Can I lose money in Sukuk?
Yes. If the asset fails or government defaults. But government Sukuk are very safe.
Q3: What is the minimum to start?
As low as $50 for Indonesia SR020.
Q4: Are Sukuk better than halal stocks?
Suk are lower risk, lower return. Stocks are higher risk, higher return. Do both.
Q5: Can non-Muslims buy Sukuk?
Yes. Anyone can buy. It’s just an asset-backed investment.
Q6: How often do Sukuk pay?
Usually every 6 months.
Q7: Is there a Sukuk ETF for USA investors?
Yes. SUK and INSU are the 2 main ones.
Q8: What happens at maturity?
You get your principal back plus final profit payment.
Q9: Are Sukuk liquid?
Government Sukuk yes. Corporate Sukuk, not always.
Q10: Which Sukuk is best for beginners?
UK Sovereign or Saudi Green Sukuk. Low risk, easy to buy.
Conclusion: Stop Letting Inflation Eat Your Savings
Look, we can’t control inflation. We can’t control interest rates.
But we CAN control where we put our money.
The 5 sharia compliant sukuk bonds for 2026_2027 give us a real option. Riba free, asset backed, and paying 4-6% in 2026.
My advice: Start small. Pick 1 Sukuk from the list above. Invest $200 and see how it feels to earn halal profit.
This is not financial advice. This is what I’m doing with my own money after 2.5 years of research.
For more Halal Finance guides visit global786trend.com
Disclaimer
This is for educational purposes only. Please consult a Shariah scholar and licensed financial advisor before investing. I am not responsible for investment decisions. Rates are accurate as of September 2026.
of sharing practical knowledge so you can invest confidently while staying true to your values. Always verify with a Shariah advisor before investing._