META DESCRIPTION Are you Muslim losing mony to riba in 2026? Learn 3 Halal ways to save money. Riba-free banking for Muslims in USA, UK, Canada, Australia.
Are Muslims Losing Money to Riba in 2026? Stop It With These 3 Halal Ways
INTRO
“Brother Yaqoob, I just calculated it… I’ve paid $47,000 in interest on my house and car.”
When a brother from Chicago told me this last month, my heart sank.
That’s the silent crisis no one talks about.
My name is Muhammad Yaqoob. For the last 3 years, I’ve been researching Halal finance for Muslims living in the West. I’ve helped families in Texas, London, Toronto, and Sydney switch from Riba to Shariah compliant options.
It’s not just in mortgages. It’s in your credit card, your savings account, your car loan, even your “cashback” rewards.
The banks are making billions from us.
But there IS a way out.
In this guide, I will show you:
- How to spot where you are Muslim losing mony to riba right now
- The 3 Halal ways to stop it starting this week
- Real banks and apps in USA, UK, Canada, Australia that are 100% Riba-free
- The 5 mistakes that keep Muslims trapped in the Riba cycle
This is not about being “too religious”. This is about protecting your wealth and your Akhirah. Let’s fix this, InshaAllah.
TABLE OF CONTENTS
- The Hidden Crisis: How We Are Muslim Losing Mony To Riba in 2026
- What Exactly Is Riba? And Why Allah Warned Us So Strongly
- Halal Way #1: Switch To Islamic Banking – No More Interest Accounts
- Halal Way #2: Ditch Interest Debt With Shariah Compliant Financing
- Halal Way #3: Invest Your Money The Halal Way, Not In Riba
- Real Banks & Apps in USA, UK, Canada, Australia for 2026
- The 5 Mistakes Muslims Make That Keep Them In Riba
- How To Calculate How Much Riba YOU Paid Last Year
- Can You Purify Riba Money? What Scholars Say
- Step-By-Step 30 Day Plan To Become Riba-Free
- FAQs: Muslim Losing Mony To Riba
- Final Advice: Protect Your Wealth + Your Deen
H2 1: The Hidden Crisis: How We Are Muslim Losing Mony To Riba in 2026
Let’s do some real math.
Average Muslim family in USA 2026:
Are Muslims Losing Money to Riba
- House Mortgage: $350,000 at 7% = ∼$250,000 paid in interest over 30 years
- 2 Car Loans: $60,000 total = ∼$8,000 in interest
- Credit Cards: $10,000 balance = ∼$2,200/year in interest
- “High Yield” Savings: Bank pays you interest = You receive Riba
Total: Over $300,000 lost to Riba in one lifetime.
That’s a house. That’s Hajj for your whole family. That’s charity that could build a masjid.
It’s the same in UK with Barclays, in Canada with RBC, in Australia with Commonwealth Bank.
The system is designed for us to stay in debt.
H2 2: What Exactly Is Riba? And Why Allah Warned Us So Strongly
Muslims Losing Money to Riba
Riba means “any guaranteed extra payment on a loan”. Simple.
Allah says: “O you who have believed, fear Allah and give up what remains of Riba, if you should be believers” [2:278]
The Prophet ﷺ said: “Allah has cursed the one who consumes Riba, the one who pays it, the one who writes it down, and the two who witness it.”
It’s that serious. Because Riba destroys 3 things:
- Your Wealth – Interest compounds against you
- Your Barakah – Money without Barakah never feels enough
- Your Society – Rich get richer, poor stay in debt
[Muslim]
If you are Muslim losing mony to riba, you are also losing Barakah.
H2 3: Halal Way #1: Switch To Islamic Banking – No More Interest Accounts
This is step 1. Stop feeding the bank Riba.
H3: The Problem With “Normal” Banks
Chase, Bank of America, Lloyds, RBC, Westpac… they all use your deposit to give interest loans to others. You become part of the Riba system.
H3: The Halal Solution 2026
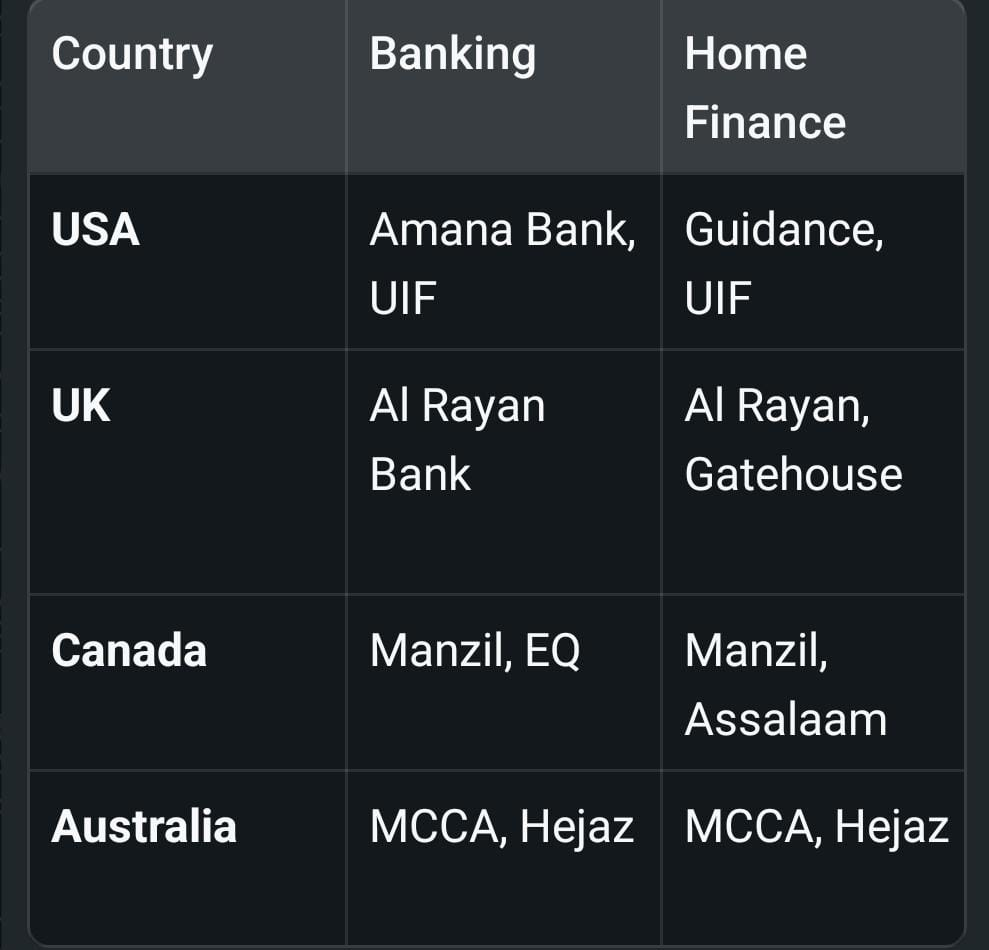
USA:
- Amana Bank – Full Islamic checking, no interest
- University Islamic Financial – Shariah compliant savings
- LaunchGood + Meezan – Digital Halal banking
UK:
- Al Rayan Bank – UK’s largest Islamic bank. Current accounts + Savings
- Gatehouse Bank – Savings accounts
Canada:
- Manzil + EQ Bank Partnership – Halal savings accounts
- Assalaam – Shariah compliant banking
Australia:
- MCCA – Islamic savings and term deposits
- Hejaz – Shariah compliant bank account
Action: Open 1 account this week. Move your salary there.
H2 4: Halal Way #2: Ditch Interest Debt With Shariah Compliant Financing
This is where most of us are Muslim losing mony to riba.
H3: For Homes – No More Conventional Mortgages
Instead of 7% interest, use:
- Murabaha: Bank buys house, sells to you at profit
- Musharaka: You + Bank co-own, you buy them out
USA 2026: Guidance Residential, UIF
UK: Al Rayan Home Purchase Plan
Canada: Manzil, EQ Halal Mortgage
Australia: MCCA, Hejaz Home Finance
H3: For Cars – No More Auto Loans
Use Ijarah – Lease to own. No interest.
USA: Devon Bank, UIF Auto
UK: Al Rayan Car Finance
H3: For Credit Cards – Cut Them Up
Use Debit Cards or Halal Charge Cards like Suk-based cards from Amana. No interest, no debt trap.
When you switch, you instantly stop being Muslim losing mony to riba every month.
H2 5: Halal Way #3: Invest Your Money The Halal Way, Not In Riba
Keeping money in a “2% interest savings account” is Riba.
H3: Halal Investment Options 2026
- Halal ETFs & Stocks
USA: HLAL, SPUS ETFs
UK: HSBC Islamic Global Equity Index
Canada: Manzil Halal ETFs
Australia: Hejaz Equities Fund - Sukuk – Islamic Bonds
Government and company Sukuk. Asset-backed, no interest. - Real Estate
Buy rental property with Halal financing. Real asset, real Barakah. - Gold & Silver
Protect from inflation. 100% Halal.
Rule: If it pays guaranteed interest, it’s Riba. If it’s profit/loss sharing, it’s Halal.
H2 6: Real Banks & Apps in USA, UK, Canada, Australia for 2026
H2 7: The 5 Mistakes Muslims Make That Keep Them In Riba
- “It’s just 5% interest, Allah will forgive” – No. Riba is major sin.
- “There are no Halal options in my city” – Yes there are. 90% are online now.
- “Halal is too expensive” – 0.5% more monthly, but you save 100% of your Barakah.
- “I’ll switch after I pay this one loan” – That “one loan” becomes 3. Switch now.
- “My bank says it’s Islamic” – Verify the Shariah board. Don’t trust marketing.
If you keep doing these, you stay Muslim losing mony to riba.
H2 8: How To Calculate How Much Riba YOU Paid Last Year
Do this tonight. It will shock you.
Step 1: Download last 12 months bank statements
Step 2: Add up: Mortgage interest + Car loan interest + Credit card interest
Step 3: Check savings account – add up “Interest Paid To You”
That number? That’s how much you are Muslim losing mony to riba.
Now imagine investing that same amount Halal way for 10 years.
H2 9: Can You Purify Riba Money? What Scholars Say
If you already received interest:
- Stop the source immediately – Close that account
- Don’t use it for yourself – Give it to charity with NO intention of reward
- Make Tawbah – Sincere repentance
Scholars in USA, UK, Canada, Australia all agree: Purify and move on. Allah is Most Merciful.
H2 10: Step-By-Step 30 Day Plan To Become Riba-Free
Week 1: Open Halal bank account. Move direct deposit.
Week 2: Apply for Halal credit card or cut up interest cards.
Week 3: Get quote for Halal home/car refinance.
Week 4: Move investments to HLAL, SPUS, or Hejaz.
30 days and you are no longer Muslim losing mony to riba.
H2 11: FAQs: Muslim Losing Mony To Riba
Q1: Is a little bit of interest ok?
A: No. Riba is Riba. Even 1 dollar.
Q2: Halal banks are slower, true?
A: Not in 2026. Amana and Al Rayan apps are faster than Chase.
Q3: Can I keep my 401k?
A: Check if it invests in Riba. Switch to Halal 401k options like Wahed or Amana.
Q4: What about student loans?
A: Refinance to interest-free family loan or Islamic student fund if available.
Q5: Are “Islamic” banks really halal?
A: Check AAOIFI certification. Guidance, Al Rayan, MCCA all certified.
Q6: I’m in debt. Where to start?
A: Stop new Riba. Avalanche method to pay off. Switch to Halal.
Q7: Is cashback halal?
A: If it comes from merchant, yes. If from interest, no.
Q8: Can non-Muslims use Islamic banks?
A: Yes. Many non-Muslims use Al Rayan for ethical banking.
Q9: What if my country has no Islamic bank?
A: Use online options. Wahed, Manzil, Amana all work internationally.
Q10: How to convince my spouse?
A: Show them the math. Show them this article. Make dua together.
H2 12: CONCLUSION – 200 words
Bhai aur behno, 2026 mein Riba se bachna pehle se zyada easy hai.
The technology is here. The banks are here. The scholars have approved the contracts.
The only question is: Will you take action?
Every month you delay, you are Muslim losing mony to riba. That money could be building your home, funding your kids’ education, or going to Sadaqah.
But more important than money is this: Allah is watching. He promised to destroy Riba and bless charity [2:276].
Start with 1 step today. Open that Halal bank account. Apply for that Halal refinance. Move $100 to a Halal ETF.
You don’t have to be perfect overnight. But you have to start.
May Allah make it easy for all of us to live Riba-free and die with wealth that is pure and full of Barakah. Ameen.
DISCLAIMER –
This article is for educational purposes only. I am Muhammad Yaqoob, not a certified financial advisor or Shariah scholar. The information about Islamic Banking, Halal investments, and Riba-free finance is based on 3 years of research and publicly available information as of 2026.
Islamic finance rulings can differ between scholars and between countries like USA, UK, Canada, and Australia. Before you open any account, sign any contract, or move any money, you MUST consult with a qualified Shariah scholar and a licensed financial professional in your country.
The companies mentioned are examples only and do not constitute financial advice or endorsement. Rates, terms, and Shariah compliance can change. It is your responsibility to verify all information directly with the provider and ensure the product meets your personal religious and financial needs. I am not responsible for any financial decisions or losses you may incur. Always do your own due diligence and seek professional advice.
of sharing practical knowledge so you can invest confidently while staying true to your values. Always verify with a Shariah advisor before investing._